Path Integrals Series: 3. The Path Integral
The path integral is a formulation of quantum mechanics originating with the physicist Feynman [5]; it is a form of functional integral, and it has become the mainstream formalism of modern quantum theory. In recent years, researchers' interest in it has grown considerably, especially regarding its applications outside the quantum domain, giving rise to works such as [7]. However, few people in China are familiar with the path integral, and many students majoring in quantum physics may never have heard of it.
From a mathematical point of view, the path integral is a method for computing the Green's function of a partial differential equation. As we know, in the study of PDEs, if one can find the corresponding Green's function, it is extremely helpful for studying the equation — but the Green's function is usually not easy to solve for. Constructing a path integral, however, only requires the Green's function over an infinitesimal time interval, so both its form and its underlying concept are quite simple.
This chapter contains nothing new; it is merely an attempt to give a concise and direct introduction to the path integral starting from the random walk problem, showing how a parabolic PDE problem can be converted into path-integral form.
From the Probability of a Point to the Probability of a Path
In our study of random walks in the previous chapter, we derived that starting from $x_0$, after time $t$, the probability density of arriving at $x_n$ is
$$\frac{1}{\sqrt{2\pi \alpha T}}\exp\left(-\frac{(x_n-x_0)^2}{2\alpha t}\right).\tag{22}$$
This is the probability of going from one point at one moment to another point at another moment; mathematically, we call this the propagator, or Green's function, of the diffusion equation $(21)$. more
Now divide the time interval into $n$ equal parts, each of length $\Delta t=\frac{T}{n}$; at time $i\Delta t$ the particle's position is $x_k$. The probability density for the particle to go from $x_k$ to $x_{k+1}$ is
$$\frac{1}{\sqrt{2\pi \alpha \Delta t}}\exp\left(-\frac{(x_{k+1}-x_k)^2}{2\alpha \Delta t}\right),\tag{23}$$
so the probability density for the particle to pass successively through $x_1,x_2,\dots,x_{n-1},x_n$ is
$$\left(\frac{1}{\sqrt{2\pi \alpha \Delta t}}\right)^n\exp\left(-\frac{(x_1-x_0)^2+(x_2-x_1)^2+\dots+(x_n-x_{n-1})^2}{2\alpha \Delta t}\right),\tag{24}$$
Let us temporarily drop the prefactors, and then take the limit $\Delta t\to 0$. We regard these points $x_0,x_1,x_2,\dots,x_{n-1},x_n$ as determining a path $(x_0,0)$ to $(x_n,T)$, call it $x(t)$, and then
$$\frac{(x_1-x_0)^2+(x_2-x_1)^2+\dots+(x_n-x_{n-1})^2}{2\alpha \Delta t}=\frac{1}{2\alpha}\sum_{k=0}^{n-1} \left(\frac{x_{k+1}-x_k}{\Delta t}\right)^2\Delta t,\tag{25}$$
As $\Delta \to 0$, we take $\frac{x_{k+1}-x_k}{\Delta t}$ to equal the derivative $\dot{x}(t_k)$ of $x(t)$ at $t_k$, so the expression above is precisely the discretized form of the integral $\frac{1}{2\alpha}\int\dot{x}^2dt$. Putting this all together, we find that the probability of the particle traveling along the path $x=x(t)$ is proportional to
$$P[x(t)] = \exp\left(-\frac{1}{2\alpha }\int\dot{x}^2dt\right).\tag{26}$$
This gives us the probability of the particle passing along the path $x(t)$, which is a functional of $x(t)$. This is exactly the path probability distribution of Brownian motion. In particular, if $\alpha=1$, it is called standard Brownian motion.
Remark:
If $W_t$ is a stochastic process satisfying the following conditions, it is called a Brownian motion:
1. $W_0=0$;
2. $\{W_t,t\geq 0\}$ is a stationary process with independent increments;
3. $\forall 0\leq s\leq t$, $W_t-W_s \sim N(0,\sigma^2(t-s))$.
When $\sigma=1$, it is called standard Brownian motion.
Summing Over Paths
We have already obtained an expression for the probability $P[x(t)]$ of a given path. The probability of going from $(x_0,0)$ to $(x_n,T)$ should then be the sum of the probabilities over all paths from $(x_0,0)$ to $(x_n,T)$. In other words, we need to sum over all paths between the two points.
This summation is carried out by discretizing the paths. As shown in Figure 1, we again divide the time interval $T$, and each path can be approximated by a broken line $x_0,x_1,x_2,\dots,x_{n-2},x_{n-1},x_n$. Therefore, to sum over all paths $x(t)$, we only need to sum over all values of $x_1,x_2,\dots,x_{n-2},x_{n-1}$ (imagine "wiggling" each of the points $x_1,x_2,\dots,x_{n-2},x_{n-1}$ up and down).
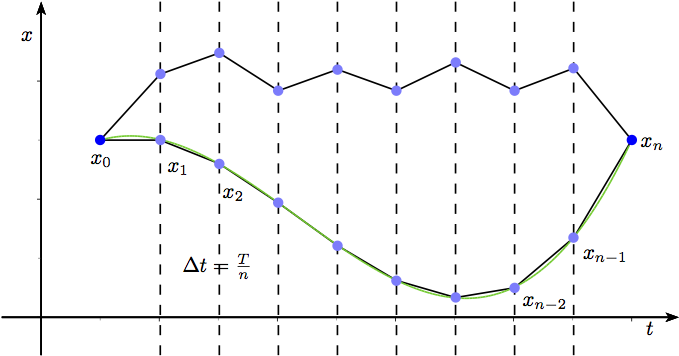 Discretizing a path and summing over
If we use $P(x_0,0;x_n,T)$ to denote the probability of going from $(x_0,0)$ to $x_n,T)$, then (for brevity, we omit the leading constant factor here — we can restore it later when working on actual problems; for now let's just get the concept straight)
$$\begin{aligned}&P(x_0,0;x_n,T)\\ =&\lim_{n\to\infty}\int_{-\infty}^{\infty} \exp\left(-\frac{1}{2\alpha}\sum_{k=0}^{n-1} \left(\frac{x_{k+1}-x_k}{\Delta t}\right)^2\Delta t\right)dx_1 dx_2\dots dx_{n-2}dx_{n-1}\end{aligned},\tag{27}$$
The integral is performed $n-1$ times, after which we take the limit $n\to\infty$. We abbreviate the expression above as
$$P(x_0,0;x_n,T)=\int_{x_0}^{x_n} P[x(t)]\mathscr{D}x(t)=\int_{x_0}^{x_n} \exp\left(-\frac{1}{2\alpha }\int_0^T\dot{x}^2dt\right)\mathscr{D}x(t),\tag{28}$$
This is called the path integral (or functional integral) of the functional $P[x(t)]$, and it is an infinite-dimensional integral.
Path Integral of the Parabolic Equation
This section aims to convert the parabolic equation $(19)$ into path-integral form. From equation $(27)$, we see that the key to constructing the path integral is to find the propagator (Green's function) over an infinitesimal time interval.
First consider $V=V(x)$, i.e., the time-independent case. Writing $H=\frac{\alpha^2}{2}\frac{\partial^2}{\partial x^2}+ V$, we abbreviate equation $(19)$ as
$$\alpha\frac{\partial \phi}{\partial t} = H\phi,\tag{29}$$
Since $H$ does not depend on $t$, the solution of the equation above can be written formally as
$$\phi(x,t)=\exp\left(\frac{1}{\alpha}t H\right)\phi(x,0)=\exp\left[\frac{1}{\alpha}t\left(\frac{\alpha^2}{2}\frac{\partial^2}{\partial x^2}+ V(x)\right)\right]\phi(x,0).\tag{30}$$
This is an exact formal solution, where $\exp\left(\frac{1}{\alpha}t H\right)$ should be understood as the operator series
$$\exp\left(\frac{1}{\alpha}t H\right)=\sum_{k=0}^{\infty} \frac{1}{k!}\frac{t^k}{\alpha^k}H^k.\tag{31}$$
We are only interested here in the result for an infinitesimal interval, i.e., taking $t=\epsilon\to 0$, so that
$$\phi(x,\epsilon)=\exp\left(\frac{\alpha}{2}\epsilon \frac{\partial^2}{\partial x^2}+\frac{1}{\alpha} \epsilon V(x)\right)\phi(x,0),\tag{32}$$
Note that $\frac{\partial^2}{\partial x^2}$ and $V(x)$ do not generally commute, so in general
$$\exp\left(\frac{\alpha}{2}\epsilon \frac{\partial^2}{\partial x^2}+\frac{1}{\alpha} \epsilon V(x)\right)\neq \exp\left(\frac{\alpha}{2}\epsilon \frac{\partial^2}{\partial x^2}\right)\exp\left(\frac{1}{\alpha} \epsilon V(x)\right),\tag{33}$$
However, to first-order approximation the two are equal (that is, their difference is second-order infinitesimal). So we have
$$\phi(x,\epsilon)=\exp\left(\frac{1}{\alpha} \epsilon V(x)\right)\exp\left(\frac{\alpha}{2}\epsilon \frac{\partial^2}{\partial x^2}\right)\phi(x,0),\tag{34}$$
Notice that
$$\hat{\phi}(x,\epsilon) = \exp\left(\frac{\alpha}{2}\epsilon \frac{\partial^2}{\partial x^2}\right)\phi(x,0),\tag{35}$$
is precisely the formal solution of the diffusion equation $\frac{\partial \hat{\phi}}{\partial t}=\frac{\alpha }{2}\frac{\partial^2 \hat{\phi}}{\partial x^2}$, and in mathematical physics we have already obtained its general solution:
$$\hat{\phi}(x,\epsilon)=\int_{-\infty}^{\infty}\frac{1}{\sqrt{2\pi\alpha\epsilon}}\exp\left(-\frac{1}{\alpha} \frac{(x-x_0)^2}{2\epsilon}\right)\phi(x_0,0)dx_0,\tag{36}$$
So equation $(34)$ equals
$$\begin{aligned}\phi(x,\epsilon)=&\exp\left(\frac{1}{\alpha} \epsilon V(x)\right)\int_{-\infty}^{\infty}\frac{1}{\sqrt{2\pi\alpha\epsilon}}\exp\left(-\frac{1}{\alpha} \frac{(x-x_0)^2}{2\epsilon}\right)\phi(x_0,0)dx_0\\ =&\frac{1}{\sqrt{2\pi\alpha\epsilon}}\int_{-\infty}^{\infty}\exp\left[-\frac{1}{\alpha} \left(\frac{1}{2}\frac{(x-x_0)^2}{\epsilon^2}-V(x)\right)\epsilon\right]\phi(x_0,0)dx_0\end{aligned},\tag{37}$$
Since this expression holds for an infinitesimal time interval, we may take $\frac{x-x_0}{\epsilon}$ to be the first-order derivative $\dot{x}$, so that the Green's function over an infinitesimal time is (omitting the leading factor)
$$\exp\left[-\frac{1}{\alpha} \left(\frac{1}{2}\dot{x}^2-V(x)\right)\epsilon\right],\tag{38}$$
From this, we can successively obtain
$$\begin{aligned}&K(x_0,0;x_n,T)\\ =&\lim_{n\to\infty}\int_{-\infty}^{\infty} \exp\left\{-\frac{1}{2\alpha}\sum_{k=0}^{n-1} \left[\left(\frac{x_{k+1}-x_k}{\Delta t}\right)^2-V(x_k)\right]\Delta t\right\}dx_1 \dots dx_{n-1}\end{aligned},\tag{39}$$
Since $\phi$ is not a probability in the strict sense, we here use $K$ to denote the propagator of $\phi$. The expression above means that the probability functional for passing along a path $x(t)$ is:
$$K[x(t)] = \exp\left[-\frac{1}{\alpha} \int_{t_a}^{t_b} \left(\frac{1}{2}\dot{x}^2-V(x)\right)dt\right],\tag{40}$$
This lets us express the probability of going from point $(x_a,t_a)$ to point $(x_b,t_b)$ as a path integral between the two points:
$$\begin{aligned}P(x_b,t_b;x_a,t_a)=&\int_{x_a}^{x_b} P[x(t)]\mathscr{D}x(t) \\ =&\int_{x_a}^{x_b}\exp\left[-\frac{1}{\alpha} \int_{t_a}^{t_b} \left(\frac{1}{2}\dot{x}^2-V(x)\right)dt\right]\mathscr{D}x(t)\end{aligned}.\tag{41}$$
The derivation above is based on the special case where $V$ is independent of time $t$, but with only minor modifications it can be extended to the time-dependent case, which we will not elaborate on here.
From the Path Integral Back to the PDE
Starting from the path functional $(40)$ and performing the path integration, one can conversely derive the partial differential equation $(19)$; the details can be found in Quantum Mechanics and Path Integrals, and will not be repeated here. Since the two can be derived from one another, this means they are equivalent: given a PDE of the form $(19)$, one can immediately write down the corresponding path functional $(40)$, and vice versa.
Some Worked Examples
The path integral is conceptually quite simple, but computing it is often extremely complex; exact solutions exist only in a small number of cases, and most of the time one has to resort to approximations. This section presents, without proof, some results drawn from Feynman's Quantum Mechanics and Path Integrals, Statistical Mechanics: A Set of Lectures, and other such works. The aim here is simply to show the reader that effective computational schemes already exist for many path-integral problems.
The Most Probable Path
We have already encountered path integrals of the form:
$$\int\exp\left(-\frac{1}{\alpha}S[x(t)]\right)\mathscr{D}(x(t).\tag{42}$$
where $S[x(t)]$ is a functional of $x(t)$; in the language of physics, it can be called the "action." Its meaning is clear: it aggregates the contributions of all paths. A natural question to ask is: which path contributes the most? If this contribution is a probability, then the question becomes: which path has the largest probability?
Clearly, for $\exp\left(-\frac{1}{\alpha}S[x(t)]\right)$ to be as large as possible, we want $S[x(t)]$ to be as small as possible — but this alone is not sufficient. The sufficient condition is that $S[x(t)]$ be as stationary as possible near $x(t)$, so that the contributions of $x(t)$ can accumulate stably. Here, "stable" means that the first-order variation of $S[x(t)]$ vanishes. From this we see that the problem of finding the most probable path in the path integral naturally leads to a "variational principle," which shows that the variational principle is intimately connected with the path integral.
For the case we discussed earlier,
$$S[x(t)]=\int_{t_a}^{t_b}\left[\frac{1}{2}\dot{x}^2-V(x,t)\right]dt,\tag{43}$$
$\delta S[x(t)]=0$ gives
$$\ddot{x}=-\frac{\partial V}{\partial x}.\tag{44}$$
with boundary condition $x(t_a)=x_a,x(t_b)=x_b$. Let its solution be $x_{cl}(t)$; substituting the solution back into $S[x(t)]$, one can compute a quantity $S_{cl}$, which is a function of $t_a,t_b,x_a,x_b$ — these notations will be useful when solving quadratic-form problems.
For the $V(x,t)$ corresponding to the random walk, we have
$$\ddot{x}=\frac{1}{2}\alpha\frac{\partial^2 p}{\partial x^2}+p\frac{\partial p}{\partial x}+\alpha \frac{\partial p}{\partial t}.\tag{45}$$
Quadratic Action
For any quadratic action, the path integral can be solved exactly, with the answer:
$$P(b,a)=\left(\frac{1}{2\pi \hbar}\right)^{D/2} \sqrt{-\det\left(\frac{\partial^2 S_{cl}}{\partial x_a \partial x_b}\right)}\exp\left(-\frac{1}{\hbar}S_{cl}\right),\tag{46}$$
where $D$ is the dimension of the space, and $\det\left(\frac{\partial^2 S_{cl}}{\partial x_a \partial x_b}\right)$ is called the van Vleck–Pauli–Morette determinant. For the proof, see [6].
Perturbative Expansion
For actions whose path integrals cannot be computed exactly, there is a perturbative expansion:
$$P(b,a)=P_0(b,a)+\left(-\frac{1}{\hbar}\right)\int P(b,c)V(c)P(c,a) d\tau_c+\left(-\frac{1}{\hbar}\right)^2\int P(b,d)V(d)P(d,c)V(c)P(c,a) d\tau_c d\tau_d. \tag{47}$$
The detailed notation and derivation can be found in Feynman's work [5].
Translated automatically with claude-sonnet-5; all equations are reproduced verbatim from the source. Copyright remains with the original author.